UK Manufacturing Cashflow Statistics (2026)
Published 17 September 2026 · Data: Companies House register of charges, September 2026
Manufacturing is the largest user of invoice finance in the United Kingdom and the slowest-paying industry in the country. Those two facts are the same fact seen from opposite ends of one supply chain.
6,365 UK manufacturing businesses hold a live invoice finance facility. New facilities are up 29% on 2019 against 28% across the market, and 13% of these borrowers are now in liquidation, administration or receivership.
- 6,365
- manufacturing businesses on a live facility
- +29%
- new facilities since 2019 (market: +28%)
- 4.8 yrs
- median facility length
- 13%
- of funded borrowers in insolvency
How many manufacturing businesses use invoice finance
Of the 34,750 UK companies on a live invoice finance or asset-based facility, 6,365 are in this sector.
| Year new facilities registered | Manufacturing | All UK |
|---|---|---|
| 2019 | 721 | 4,498 |
| 2020 | 492 | 3,039 |
| 2021 | 551 | 4,003 |
| 2022 | 684 | 4,034 |
| 2023 | 698 | 4,493 |
| 2024 | 720 | 5,172 |
| 2025 | 932 | 5,764 |
The reason is inventory. A manufacturer buys materials, converts them over weeks, ships, then waits sixty days. Working capital is tied up at every stage and the invoice is the only part of the chain a lender will readily advance against.
How long a facility lasts in this sector
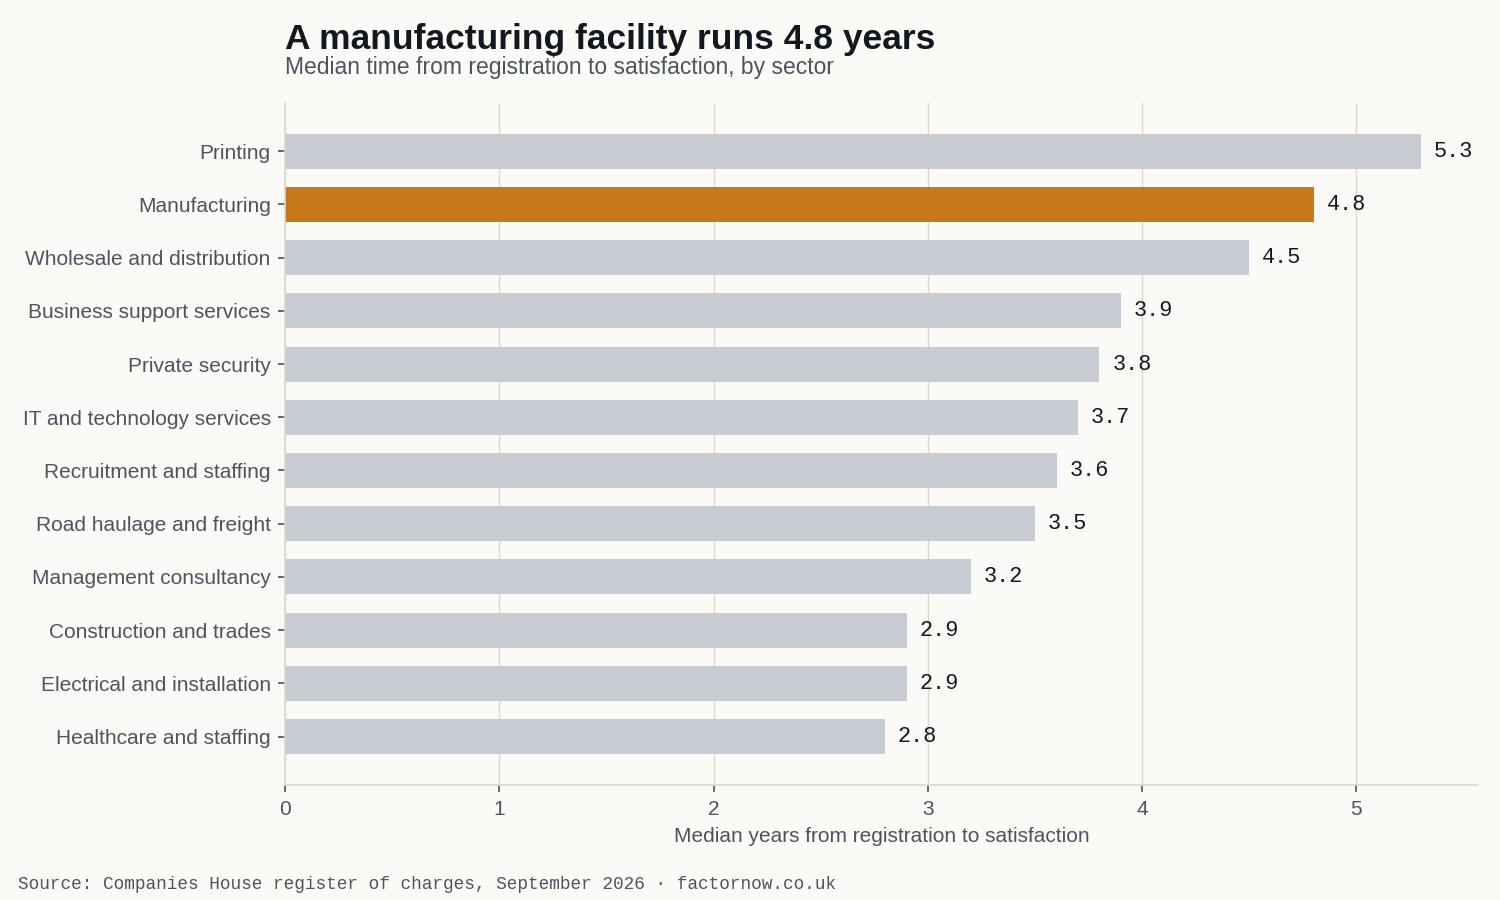
The median facility in this sector runs 4.8 years between registration and satisfaction. Across the twelve largest funded sectors that ranges from 2.8 years in healthcare to 5.4 years in printing.
A short median is not a bad sign. It can mean smaller arrangements, or clients who outgrow the facility. A long one suggests a deeper, stickier asset-based relationship. Either way, if you are being sold a facility the useful question is what the exit looks like: termination notice periods and minimum terms are where the cost of leaving sits, and they are rarely the part of the proposal anyone reads closely.
How many businesses change provider
21% of funded businesses in this sector have used more than one invoice finance provider. Across sectors that runs from 11% in management consultancy to 23% in recruitment.
Switching is more common than most business owners assume, and the register only counts moves that left a trace - a facility that ended and was replaced. It does not capture businesses that renegotiated and stayed, so the real figure is higher.
Bank or independent?
| Type of lender | Share of facilities in this sector |
|---|---|
| Bank-owned invoice finance arms | 71% |
| Independent specialists | 25% |
The two halves of this market behave differently. Bank-owned facilities tend to be larger and cheaper, with tighter limits on how much of your ledger can sit with a single customer. Independents are generally more flexible on concentration, on construction-style debt and on export invoices, and quicker to decide. Neither is better in the abstract; which one fits depends on your ledger.
Where it is used
| Region | Businesses on a live facility |
|---|---|
| North West | 1,121 |
| West Midlands | 1,087 |
| Yorkshire | 939 |
| South East | 737 |
| East | 736 |
Failure rate
13% of manufacturing businesses holding a facility are in liquidation, administration or receivership. Across the twelve largest funded sectors the range runs from 8.5% in wholesale to 17.1% in printing.
What the sector gets paid
Large manufacturers take a median of 45 days to pay their own suppliers, the slowest of any sector against an all-sector median of 32. So a manufacturer is typically waiting on another manufacturer, and the smallest supplier at the end of the chain absorbs the lot.
Method
Companies House register of charges, full extract, September 2026. Charges recorded as outstanding and held by an identified invoice finance or asset-based lender, matched at entity level: where a lender registers invoice finance through a named subsidiary, only that subsidiary counts, because the parent's charges cover lending that cannot be separated from it. Charge type is not filtered - only 78% of these lenders' live charges carry a floating charge over all assets and 15% carry no type flag at all.
Barclays and AIB are excluded entirely. Both register all lending under the parent bank with no separate invoice finance entity, so their books cannot be isolated. Both are real providers, so the true totals are larger than those shown.