London Business Cashflow Statistics (2026)
Published 30 September 2026 · Data: Companies House register of charges, September 2026
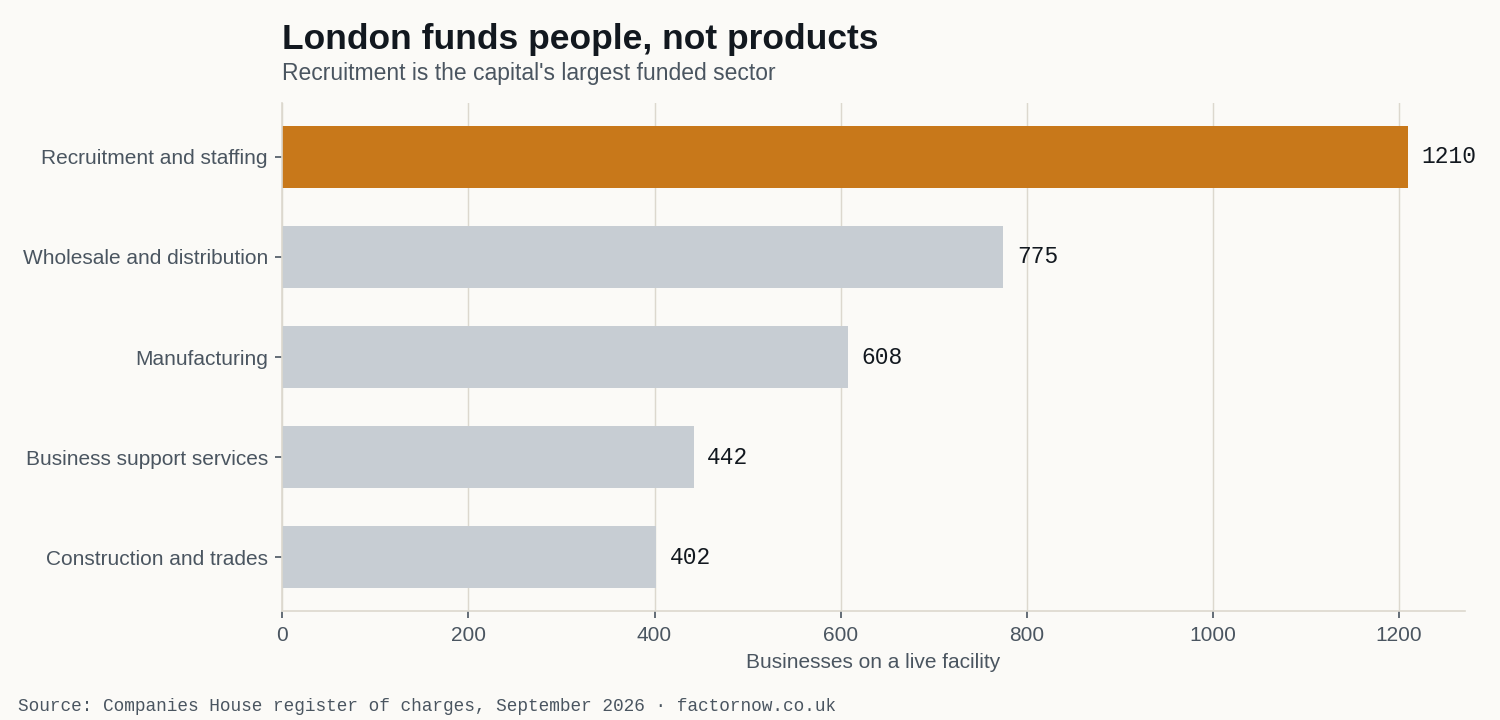
London has more businesses on invoice finance than any other part of the United Kingdom. Its distinction is what it funds rather than how much.
5,870 businesses in the region hold a live invoice finance facility. New facilities are up 32% on 2019 against 28% nationally, and 12.7% of those borrowers are in liquidation or administration.
- 5,870
- businesses in London on a live facility
- +32%
- new facilities since 2019 (market: +28%)
- 3.6 yrs
- median facility length
- 12.7%
- of funded borrowers in insolvency
New facilities registered each year
| Year new facilities registered | London | All UK |
|---|---|---|
| 2019 | 816 | 4,498 |
| 2020 | 539 | 3,039 |
| 2021 | 796 | 4,003 |
| 2022 | 743 | 4,034 |
| 2023 | 830 | 4,493 |
| 2024 | 905 | 5,172 |
| 2025 | 1,074 | 5,764 |
What the region funds
| Sector | Businesses on a live facility |
|---|---|
| Recruitment and staffing | 1,210 |
| Wholesale and distribution | 775 |
| Manufacturing | 608 |
| Business support services | 442 |
| Construction and trades | 402 |
How long a facility lasts in the region
The median facility in the region runs 3.6 years between registration and satisfaction. Across the twelve largest funded sectors that ranges from 2.8 years in healthcare to 5.4 years in printing.
A short median is not a bad sign. It can mean smaller arrangements, or clients who outgrow the facility. A long one suggests a deeper, stickier asset-based relationship. Either way, if you are being sold a facility the useful question is what the exit looks like: termination notice periods and minimum terms are where the cost of leaving sits, and they are rarely the part of the proposal anyone reads closely.
How many businesses change provider
17% of funded businesses in the region have used more than one invoice finance provider. Across sectors that runs from 11% in management consultancy to 23% in recruitment.
Switching is more common than most business owners assume, and the register only counts moves that left a trace - a facility that ended and was replaced. It does not capture businesses that renegotiated and stayed, so the real figure is higher.
Bank or independent?
| Type of lender | Share of facilities in the region |
|---|---|
| Bank-owned invoice finance arms | 52% |
| Independent specialists | 44% |
The two halves of this market behave differently. Bank-owned facilities tend to be larger and cheaper, with tighter limits on how much of your ledger can sit with a single customer. Independents are generally more flexible on concentration, on construction-style debt and on export invoices, and quicker to decide. Neither is better in the abstract; which one fits depends on your ledger.
Failure rate
12.7% of funded businesses in the region are in liquidation, administration or receivership. Across the eight largest regions the range runs from 9.0% in the South East to 17.4% in the North West.
Method
Companies House register of charges, full extract, September 2026. Charges recorded as outstanding and held by an identified invoice finance or asset-based lender, matched at entity level: where a lender registers invoice finance through a named subsidiary, only that subsidiary counts, because the parent's charges cover lending that cannot be separated from it. Charge type is not filtered - only 78% of these lenders' live charges carry a floating charge over all assets and 15% carry no type flag at all. Regions are assigned from the postcode of the company's registered office, which for a business trading nationally may not be where the work happens.
Barclays and AIB are excluded entirely. Both register all lending under the parent bank with no separate invoice finance entity, so their books cannot be isolated. Both are real providers, so the true totals are larger than those shown.